Starting February 2, 2026, the FDA’s Quality Management System Regulation will officially harmonize U.S. standards with the international ISO 13485:2016 framework. This landmark shift represents more than just a bureaucratic realignment; it signals a fundamental change in the global medical device testing market, which is now navigating a period of unprecedented expansion and technical scrutiny. Valued at USD 11.3 billion in 2025, the market is currently projected to climb to USD 28.1 billion by 2036, maintaining a steady compound annual growth rate of 8.6% throughout this ten-year window. The rapid evolution of healthcare technology, from sophisticated implants to AI-driven diagnostic tools, has necessitated a parallel advancement in testing methodologies. As we move deeper into 2026, the emphasis has shifted from simple compliance to a comprehensive, data-driven assurance of patient safety. Manufacturers are no longer treating testing as a final gatekeeping hurdle but as an integral component of the entire product lifecycle. This transition is fueled by a global ecosystem that prioritizes clinical evidence and long-term performance over speed-to-market. Consequently, the demand for third-party laboratory services has surged, as the technical requirements for verification and validation become too complex for many firms to manage internally, thereby setting the stage for a decade of sustained growth and industrial modernization across the medical landscape.
Strategic Segment Analysis: The Centrality of Laboratory Data
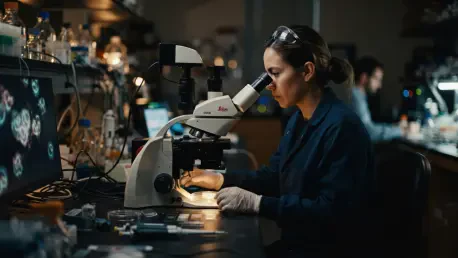
Within the broader medical device testing ecosystem, laboratory-based services have solidified their position as the dominant force, currently commanding a 48.3% share of the total market value. This concentration is largely due to the fact that empirical laboratory data serves as the non-negotiable foundation for every regulatory submission across the globe. Whether a manufacturer is pursuing a 510(k) clearance in the United States or a CE mark under the European Medical Device Regulation, they must provide exhaustive proof of biological safety, electrical reliability, and structural integrity. Unlike inspection or certification phases, which typically occur toward the end of a product’s development, testing is a recurring necessity that begins during the prototype stage and continues through post-market surveillance. Each device often requires dozens of specialized tests, ranging from shelf-life validation to mechanical fatigue assessments, ensuring a high volume of work for accredited facilities. This recurring demand, paired with the specialized equipment required to conduct these evaluations, has turned testing into a primary revenue driver for global service providers.
While certification and inspection remain vital for maintaining high manufacturing standards, the sheer technical complexity of modern medical devices keeps the focus on rigorous laboratory evaluation. Certification acts as the final seal of approval, yet it is the underlying test reports that provide the technical justification for that seal. As devices become more integrated with electronic components and wireless capabilities, the scope of testing continues to broaden. Laboratories must now offer a multidisciplinary approach, combining traditional mechanical testing with electromagnetic compatibility and cybersecurity assessments. This shift toward “multi-faceted validation” means that a single product often stays within the laboratory environment for longer periods, undergoing a battery of tests that were not required a decade ago. The integration of laboratory services into the early design phase has also helped manufacturers identify potential failures before they become costly regulatory roadblocks, further embedding laboratory data into the heart of the medical device commercialization process.
Device Classification: Navigating the Complexity of Class II Systems
The market for medical device testing is heavily influenced by the risk profiles of the products being evaluated, with Class II devices currently accounting for 51.4% of the total market value. These moderate-risk items, which include essential clinical tools like infusion pumps, patient monitors, and powered surgical instruments, represent the high-volume core of the healthcare industry. Their dominance in the testing market stems from a “Goldilocks” balance of production scale and regulatory oversight. Unlike Class I devices, which are often low-risk and require minimal external testing, or Class III devices, which are high-risk but produced in smaller quantities, Class II products are manufactured by the millions and require comprehensive validation to ensure they do not malfunction during routine clinical use. The technical requirements for Class II devices have become significantly more stringent over the last twelve months, particularly regarding their electronic safety and the durability of the materials used in their construction.
The high market share of Class II testing is also driven by the increasing technological sophistication of these devices, many of which now feature wireless connectivity and complex user interfaces. For example, a standard patient monitor is no longer just a display screen; it is a networked device that must undergo rigorous electromagnetic interference testing and software verification. The trend toward portable and home-use medical devices has further complicated this segment, as these products must be tested for safety in non-clinical environments where power supplies may be unstable and user errors are more likely. Consequently, manufacturers of Class II devices are significantly increasing their outsourcing budgets to leverage the expertise of external laboratories that can provide specialized testing for wireless coexistence and battery safety. This surge in volume and complexity ensures that the Class II segment will remain the primary engine of growth for the testing industry as manufacturers scramble to update their technical files to meet the latest global standards.
Biocompatibility Standards: Risk Management in Human Interfaces
Biocompatibility testing has emerged as one of the most critical and scrutinized sectors of the industry, currently capturing roughly 28.4% of the market spend. This specialized field focuses on how medical materials interact with human biological systems, ensuring that implants, catheters, and even simple surgical tools do not trigger adverse reactions like cytotoxicity, sensitization, or chronic inflammation. The industry is presently in a state of transition following the late 2025 updates to the ISO 10993-1 standard, which moved the industry away from a “check-box” approach toward a more nuanced, risk-management-based framework. This shift requires laboratories to provide much more than simple pass/fail results; they must now offer detailed chemical characterization and toxicological risk assessments. This increased demand for high-level scientific analysis has made biocompatibility one of the most expensive and time-consuming phases of device development, as it often involves long-term studies and sophisticated analytical chemistry.
The heightened focus on biological safety is not limited to permanent implants; it now extends to any device that has even transient contact with a patient. Modern regulators are increasingly concerned about the long-term effects of leachable and extractable substances, which are chemicals that can migrate from a device into a patient’s body over time. This concern has led to a surge in demand for high-resolution mass spectrometry and other advanced analytical techniques that can detect trace amounts of potentially harmful compounds. Furthermore, the move toward sustainable materials and new polymer formulations in device manufacturing has created a need for novel testing protocols that can accurately predict how these materials will behave over years of use. As a result, laboratories that specialize in biocompatibility are expanding their toxicological expertise, moving beyond animal testing to incorporate in-vitro models and computational modeling to provide a more comprehensive safety profile for new medical technologies.
End-User Dynamics: The Critical Role of Hospital Infrastructure
Hospitals and clinical healthcare facilities represent the largest end-user segment for medical device testing services, accounting for approximately 38.2% of the market expenditure. While device manufacturers are responsible for the extensive pre-market testing required to launch a product, hospitals carry the burden of “in-service” testing and ongoing maintenance. Every piece of equipment in a modern hospital, from life-support ventilators to mobile X-ray units, must undergo regular electrical safety checks and performance calibration to ensure patient and staff safety. As healthcare systems become increasingly digitized, the role of biomedical engineering departments within these institutions has expanded to include the management of massive fleets of interconnected devices. This has created a significant demand for third-party calibration and testing services that can verify the accuracy and safety of equipment after repairs or during routine annual audits.
The demand for testing within the hospital environment is also being driven by the need for rigorous acceptance testing of new equipment. When a hospital purchases a new fleet of infusion pumps or patient monitors, they do not simply put them into service; they must first verify that each unit meets the manufacturer’s specifications and complies with local safety regulations. This process is essential for mitigating liability and ensuring that the high-stakes clinical environment remains safe for patients. Moreover, as hospitals adopt more wearable health technology and remote monitoring tools, the complexity of managing these devices increases. Biomedical engineers must now ensure that these tools maintain their performance accuracy even when used outside the controlled hospital network. This ongoing need for localized, high-frequency testing and verification ensures that the hospital segment remains a stable and growing contributor to the overall medical device testing market throughout the forecast period.
Regional Analysis: The Expansion of the American Testing Landscape
The United States currently stands as the fastest-growing major market for medical device testing, boasting a projected 10.0% compound annual growth rate. This robust growth is supported by an enormous domestic industry consisting of over 29,000 registered medical device establishments, ranging from global giants to specialized startups. The primary catalyst for this recent surge is the implementation of the FDA’s Quality Management System Regulation (QMSR), which took full effect in early 2026. By harmonizing U.S. quality standards with the international ISO 13485 framework, the FDA has fundamentally changed the documentation and validation requirements for both domestic and foreign manufacturers selling in the American market. This shift has forced companies to conduct extensive gap analyses and re-validate many of their existing processes, leading to a massive increase in the demand for professional testing and advisory services across the country.
Beyond regulatory changes, the American market is also benefiting from a strong trend toward domestic manufacturing and a heightened focus on supply chain resilience. Manufacturers are increasingly looking for testing partners that are geographically close to their production hubs in the Midwest and California to reduce logistics costs and speed up the development cycle. The explosion of digital health and “hospital-at-home” technologies in the U.S. has also added a new layer of complexity to the testing market. Devices that were once simple mechanical tools are now integrated with sensors and cloud connectivity, requiring specialized laboratories that can handle both traditional safety testing and modern cybersecurity verification. This unique combination of a massive existing manufacturing base, a modernized regulatory framework, and a high rate of technological innovation ensures that the United States will continue to lead the global market in terms of both value and growth rate over the coming decade.
European Integration: Regulatory Convergence and the German Market
Europe remains a critical hub for medical device innovation, with Germany leading the region with an expected 8.7% growth rate. The European market is currently navigating the final phases of transition toward the Medical Device Regulation (MDR) and the In-Vitro Diagnostic Regulation (IVDR), which have significantly raised the bar for clinical evidence and technical documentation. In May 2026, the mandatory adoption of several EUDAMED modules and the implementation of standardized conformity assessment rules across the European Union have further streamlined how devices are tracked and validated. These changes have eliminated many of the legacy pathways that allowed older devices to remain on the market without modern testing data. As a result, manufacturers across Germany and the rest of Europe are engaged in a continuous cycle of re-testing and re-certification to ensure their entire product portfolios remain compliant with the new, more stringent legal landscape.
To keep pace with this surging demand, global laboratory leaders have been aggressively expanding their presence in Germany, particularly in regions with high concentrations of orthopedic and cardiovascular manufacturing. New facilities are being built specifically to handle the specialized needs of the European market, such as sterile barrier system validation and advanced microbiology testing. The focus in the European market is also shifting toward “active” post-market surveillance, where manufacturers are required to gather and test field data throughout the entire life of the device. This requirement has created a new category of recurring testing services, as companies must now periodically re-verify the performance and safety of their products based on real-world usage. This environment of high regulatory standards and technical excellence makes Germany and the broader European market a cornerstone of the global testing industry, driving innovation in both methodology and service delivery.
Global Reach: Sustaining Growth in Japan and Emerging Economies
Japan continues to be a major force in the medical device testing market, supported by an 8.2% growth rate and an aging population that demands increasingly sophisticated therapeutic and diagnostic tools. The Japanese Pharmaceuticals and Medical Devices Agency (PMDA) has become a global leader in the regulation of software-as-a-medical-device (SaMD), creating a unique niche for testing laboratories that specialize in software verification and algorithmic safety. As Japanese manufacturers push to expand their presence in international markets, they are increasingly relying on laboratories that hold global accreditations, allowing them to satisfy the requirements of the FDA, the EU, and the PMDA with a single coordinated testing program. This focus on international harmonization has made the Japanese market highly efficient, even as the technical complexity of the devices being produced continues to rise.
In contrast, emerging markets like Brazil and the United Kingdom are carving out their own paths with specialized regulatory frameworks. The UK, following its departure from the European Union, has established a robust domestic system under the MHRA, which emphasizes proactive post-market surveillance and rapid safety updates. This has led to a 7.5% growth rate as manufacturers adapt to these unique British requirements. Meanwhile, Brazil has seen a 6.3% increase in market activity following ANVISA’s publication of recognized technical standards in late 2026. By aligning its domestic standards with international norms, Brazil has simplified the process for local manufacturers to export their products while making it easier for global firms to enter the South American market. These regional developments illustrate that while the core principles of medical device testing are global, the implementation remains localized, requiring laboratories to possess deep knowledge of multiple regulatory jurisdictions to succeed.
Market Drivers: Technological Complexity and Connectivity Requirements
One of the most powerful drivers of the medical device testing market is the rapid integration of Internet of Things (IoT) technology into traditional clinical tools. We have moved beyond an era where a surgical instrument was merely a piece of stainless steel; today, many devices are networked systems that transmit real-time patient data to electronic health records. This connectivity has introduced an entirely new category of testing requirements, including electromagnetic compatibility (EMC), wireless coexistence, and robust cybersecurity protocols. A device that works perfectly in a vacuum may fail in a crowded hospital environment where dozens of other wireless signals are competing for bandwidth. Consequently, laboratories must now simulate these complex environments to ensure that life-critical devices do not lose connectivity or suffer from interference. This technological shift has turned what was once a straightforward mechanical evaluation into a sophisticated multi-disciplinary engineering challenge.
In addition to connectivity, the use of innovative materials and manufacturing techniques is pushing the boundaries of traditional testing. The rise of 3D-printed implants made from titanium and specialized polymers has forced the industry to develop bespoke testing protocols that can account for the unique structural properties of additive manufacturing. Traditional “off-the-shelf” tests are often insufficient for these personalized medical devices, which may have complex internal geometries that are difficult to sterilize or inspect. Furthermore, the development of bio-absorbable materials—which are designed to dissolve in the body after they have performed their function—requires long-term longitudinal studies to ensure that the degradation products do not cause toxic reactions. This constant cycle of material innovation ensures that the testing market remains dynamic, as each new breakthrough in device design necessitates a corresponding breakthrough in safety validation and performance verification.
Industry Restraints: Infrastructure Demands and Talent Scarcity
Despite the clear trajectory for growth, the medical device testing industry faces significant structural challenges, most notably the astronomical costs associated with building and maintaining high-end laboratory infrastructure. Establishing a facility capable of performing advanced biocompatibility, radiation sterilization validation, or high-level electromagnetic testing requires an investment of tens of millions of dollars. These facilities must not only house incredibly expensive diagnostic equipment but also maintain strict environmental controls and adhere to rigorous quality management systems like ISO 17025. These high capital requirements act as a significant barrier to entry, concentrating the market in the hands of a few global players and making it difficult for smaller, specialized labs to compete on a global scale. This concentration can sometimes lead to bottlenecks in the supply chain, particularly when a major regulatory change triggers a sudden surge in demand for specific types of testing.
Beyond the physical infrastructure, the industry is grappling with a chronic shortage of highly specialized human capital. The technical nature of medical device testing requires a workforce of PhD-level toxicologists, expert microbiologists, and engineers who deeply understand both the science of testing and the nuances of global regulatory law. As the market expands, the competition for this talent has become fierce, often limiting a laboratory’s capacity more than its physical equipment ever could. Training a new regulatory affairs expert or a specialist in chemical characterization can take years, and the rapid pace of technological change means that even experienced professionals must constantly update their skills. This talent gap is a major restraint on the market’s total potential, as it can lead to longer turnaround times for manufacturers and higher costs for the specialized services that remain in high demand.
Competitive Strategies: The Convergence of Scale and Specialization
The competitive landscape of the medical device testing market is currently defined by a strategic split between broad-spectrum global giants and highly focused specialist laboratories. Companies such as SGS, UL Solutions, and Intertek have positioned themselves as “one-stop-shop” providers, offering everything from initial electrical safety checks to final quality system certification and environmental auditing. Their competitive advantage lies in their massive global footprint, which allows them to manage complex, multi-market projects for large multinational manufacturers. By offering a unified quality system across their various locations, these giants minimize the administrative burden for their clients, making it easier to coordinate the hundreds of individual tests required for a global product launch. This scale also allows them to invest in the most advanced digital tools for data management and client reporting, further streamlining the validation process.
On the other end of the spectrum, specialized life science laboratories like Nelson Labs, NAMSA, and Eurofins Scientific have built their reputations on deep scientific expertise in specific niches such as sterility assurance and preclinical biocompatibility. These organizations are often the preferred partners for high-risk Class III devices and innovative new technologies that require custom-designed testing protocols. For instance, Nelson Labs’ recent expansion of its cleanroom capacity and the launch of rapid sterility testing services demonstrate a commitment to addressing the specific pain points of the medical industry. These specialists differentiate themselves by acting as scientific consultants rather than just service providers, helping manufacturers navigate the complex toxicological and biological questions that arise during the development of advanced implants. This balance between the efficiency of the global giants and the expertise of the specialists creates a healthy, competitive ecosystem that can address the diverse needs of the entire medical device industry.
Operational Excellence: Navigating Fragmentation and Timeline Hurdles
One of the primary operational challenges facing both manufacturers and testing laboratories is the persistent fragmentation of global regulatory requirements. Despite significant efforts toward international harmonization, such as the FDA’s adoption of ISO 13485 and the growth of the Medical Device Single Audit Program, notable differences remain between the major markets. A biocompatibility study that satisfies the FDA might still require additional data points for the NMPA in China or ANVISA in Brazil. This redundancy forces manufacturers to conduct multiple rounds of testing for what is essentially the same product, increasing costs and extending the time it takes to reach patients. Laboratories that can effectively manage these global differences by designing “universal” test plans are increasingly in high demand, as they provide a much-needed bridge between the various regional regulatory silos.
The length of testing timelines also remains a significant friction point in the product development cycle. Certain biological evaluations, such as chronic toxicity or carcinogenicity studies, can take months or even years to complete, often becoming the longest pole in the tent for a product’s market entry. These long lead times are inherent to the science of biological safety, as there are currently few shortcuts for observing the long-term effects of a device on living tissue. However, the industry is actively working to mitigate these delays through the development of “rapid testing” technologies and the increased use of in-silico modeling. By using computer simulations to predict how a device will interact with biological systems, manufacturers can refine their designs before starting the formal, long-term laboratory tests. While these digital tools will not replace traditional testing in the near term, they are becoming an essential part of an efficient validation strategy designed to reduce the overall time-to-market.
Strategic Next Steps: Transforming Safety into a Competitive Advantage
As the medical device testing market moved toward its 2036 valuation of USD 28.1 billion, the industry successfully transitioned from viewing safety data as a regulatory burden to recognizing it as a primary competitive advantage. Leading manufacturers realized that having robust, transparent, and high-quality testing data allowed them to gain market access faster and build deeper trust with clinical end-users. By integrating safety experts into the earliest stages of product design, companies were able to identify and resolve potential issues long before they reached the expensive final validation phase. This “Design for Excellence” approach became the standard for the industry, ensuring that new technologies were not just innovative in their function, but also fundamentally safe and reliable in their construction. This strategic shift helped to minimize the risk of costly product recalls and protected the long-term reputation of healthcare brands in an increasingly scrutinized global market.
Healthcare providers and hospital systems also played a vital role in this evolution by demanding higher standards of evidence and more rigorous in-service maintenance protocols. By aligning their internal engineering practices with the sophisticated data provided by manufacturers, hospitals were able to reduce equipment downtime and improve patient outcomes. The investment in laboratory capacity and the development of new, rapid testing methodologies also bore fruit, as the industry became more agile in responding to emerging health challenges and new material innovations. Ultimately, the growth of the testing market reflected a global commitment to the idea that the success of medical technology is inseparable from the data that proves its safety. Those organizations that prioritized rigorous validation and embraced the complexity of modern regulatory requirements found themselves best positioned to lead the healthcare industry into a safer and more technologically advanced future.